
Managing personal expenses is an important part of building a healthy financial life. Whether you earn a small income or a high salary, it is possible to lose track of your money if you do not have a clear spending plan.
Personal expense management is not about avoiding every purchase or living an extremely restrictive lifestyle. It is about understanding where your money goes, making thoughtful spending decisions, and ensuring that your expenses match your financial goals.
When you manage your expenses effectively, you can reduce unnecessary spending, save more money, avoid financial stress, and make better decisions about your future.
In this guide, you will learn practical ways to manage your personal expenses, create spending limits, track your money, and develop better financial habits.
What Are Personal Expenses?
Personal expenses are the costs you pay for your everyday life and personal needs.
They can include:
- Housing
- Food and groceries
- Transportation
- Utility bills
- Phone and internet
- Healthcare
- Clothing
- Entertainment
- Shopping
- Education
- Insurance
- Debt payments
- Personal care
- Subscriptions
Some expenses are necessary, while others are optional.
Understanding the difference between these categories is one of the first steps toward better money management.
Why Is Managing Personal Expenses Important?
Without proper expense management, it can be difficult to understand why you are running out of money before the end of the month.
Managing your expenses can help you:
- Stay within your income
- Reduce unnecessary spending
- Increase your savings
- Prepare for emergencies
- Pay bills on time
- Reduce debt
- Reach financial goals
- Reduce financial stress
For example, if you discover that you are spending $300 every month on unnecessary purchases, reducing that amount could potentially give you an additional $3,600 over a year.
Small changes can make a significant difference when they are repeated consistently.
Step 1: Know Your Monthly Income
Before managing your expenses, you need to know how much money you have available.
Calculate your monthly take-home income rather than using your gross salary.
Your income may come from:
- Employment
- Freelance work
- Business activities
- Side jobs
- Rental income
- Investments
- Other regular sources
If your income changes every month, consider using a conservative average based on your recent income.
Knowing your actual available income gives you a starting point for building a realistic spending plan.
Step 2: Track Every Expense
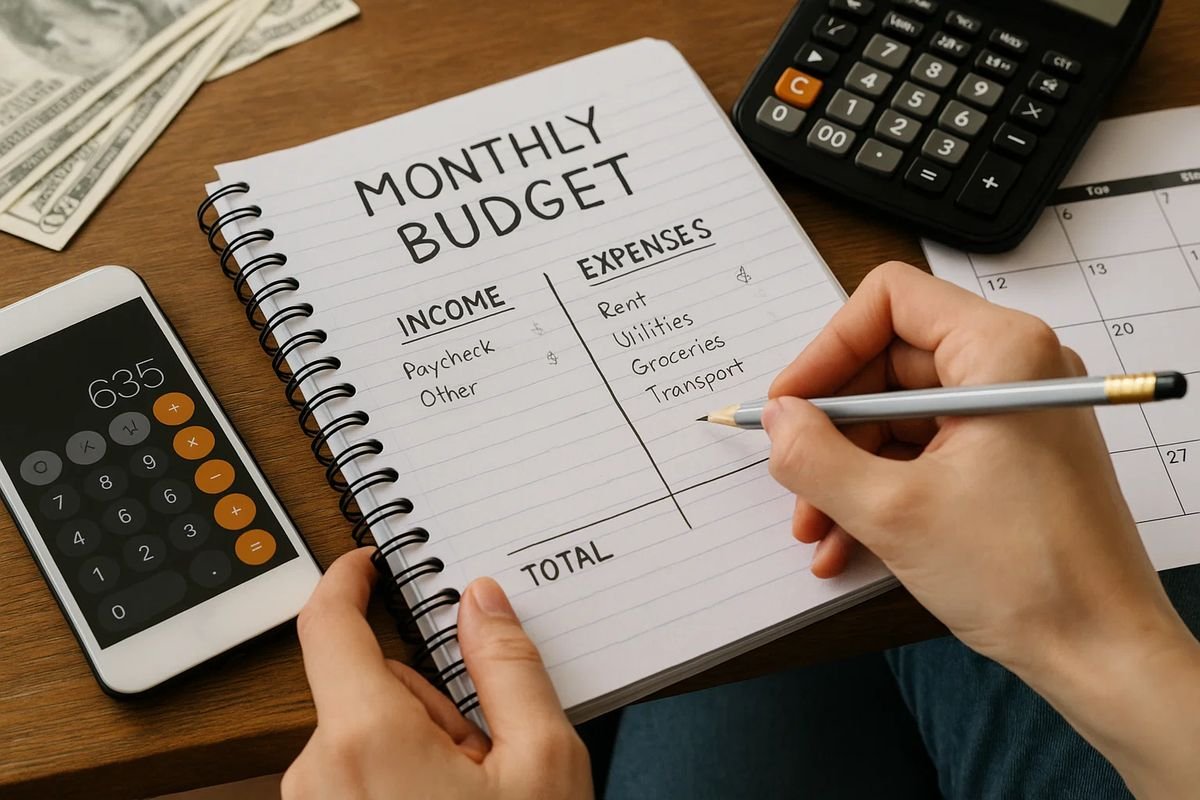
One of the most important steps in managing personal expenses is tracking your spending.
For at least one month, record everything you spend.
This includes both large and small purchases.
For example:
- $500 rent
- $100 groceries
- $40 transportation
- $15 coffee
- $30 online shopping
- $20 entertainment
Small purchases are easy to ignore, but they can become significant when repeated regularly.
You can track expenses using a spreadsheet, notebook, budgeting app, or your bank transaction history.
The method does not matter as much as consistency.
Step 3: Divide Expenses Into Categories
After tracking your spending, organize your expenses into categories.
A simple system might include:
Housing
Rent, mortgage, maintenance, and other housing costs.
Food
Groceries, restaurants, delivery, and snacks.
Transportation
Fuel, public transportation, car payments, repairs, and parking.
Utilities
Electricity, water, gas, phone, and internet.
Personal
Clothing, personal care, hobbies, and other personal expenses.
Entertainment
Movies, games, events, streaming services, and recreational activities.
Financial
Debt payments, savings, investments, and insurance.
Categorizing expenses helps you identify where most of your money is going.
Step 4: Separate Needs From Wants
Not every expense has the same level of importance.
A useful approach is to divide expenses into needs and wants.
Needs are expenses that are essential for daily life, such as:
- Housing
- Basic food
- Utilities
- Essential transportation
- Healthcare
- Required debt payments
Wants are expenses that improve your lifestyle but are not essential.
These can include:
- Dining out
- Entertainment
- New gadgets
- Expensive clothing
- Premium subscriptions
- Luxury purchases
You do not have to eliminate wants.
Instead, decide how much you can comfortably spend on them after covering your essential expenses and financial goals.
Step 5: Create Spending Limits
Once you understand your expenses, create a spending limit for each category.
For example:
| Category | Monthly Limit |
|---|---|
| Housing | $800 |
| Groceries | $350 |
| Transportation | $200 |
| Utilities | $150 |
| Personal | $100 |
| Entertainment | $100 |
| Savings | $500 |
Your actual numbers will depend on your income and circumstances.
The purpose of spending limits is to give every category a clear boundary.
If you spend more than expected in one category, look for ways to reduce spending elsewhere rather than ignoring the problem.
Step 6: Prioritize Essential Bills
Essential bills should be paid before optional spending.
At the beginning of each month, identify the expenses that must be covered.
These might include:
- Rent or mortgage
- Utilities
- Insurance
- Loan payments
- Groceries
- Transportation
- Healthcare
Make sure these costs are included in your budget before allocating money to entertainment or non-essential shopping.
This helps prevent important bills from becoming a financial emergency.
Step 7: Reduce Unnecessary Expenses
After reviewing your spending, identify expenses that do not provide enough value.
Look for things such as:
- Unused subscriptions
- Frequent restaurant meals
- Impulse shopping
- Expensive convenience purchases
- Unnecessary fees
- Duplicate services
- Purchases you rarely use
You do not need to eliminate everything.
Instead, focus on expenses that you can reduce without significantly affecting your quality of life.
For example, if you spend $200 per month on restaurant meals, reducing that amount to $150 could free up $50 for savings.
Step 8: Control Impulse Purchases
Impulse spending can make managing personal expenses much more difficult.
An impulse purchase often happens when you buy something without planning for it.
To reduce impulse purchases, try the 24-hour rule.
If something is not essential, wait at least one day before buying it.
For expensive purchases, consider waiting even longer.
During the waiting period, ask:
- Do I need this?
- Can I afford it?
- Do I already own something similar?
- Will I still want it later?
- Does this purchase support my financial goals?
This short pause can prevent many unnecessary purchases.
Step 9: Use the 50/30/20 Rule as a Starting Point
The 50/30/20 method is a popular way to organize personal expenses.
It suggests allocating approximately:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
For example, if your monthly income is $3,000:
- $1,500 could go toward needs
- $900 toward wants
- $600 toward savings and debt
However, this is only a guideline.
Your actual budget may look different because of housing costs, family responsibilities, debt, location, or income.
Use the concept as a starting point rather than a strict rule.
Step 10: Manage Recurring Expenses
Recurring expenses deserve special attention because they automatically take money from your budget every month.
Examples include:
- Streaming services
- Phone plans
- Internet
- Gym memberships
- Software subscriptions
- Insurance
- Loan payments
Review these expenses regularly.
Ask whether each service is still necessary and whether a cheaper alternative is available.
Reducing recurring expenses can be especially valuable because the savings continue month after month.
Step 11: Plan for Irregular Expenses
Some expenses happen only occasionally.
Examples include:
- Vehicle repairs
- Annual insurance
- School expenses
- Holiday shopping
- Home maintenance
- Medical expenses
- Gifts
These costs can disrupt your budget if you do not prepare for them.
One solution is to create separate savings categories for predictable irregular expenses.
For example, if you expect to spend $600 on annual vehicle maintenance, you could set aside approximately $50 per month.
When the expense arrives, the money is already available.
Step 12: Build an Emergency Fund
An emergency fund is one of the most important parts of personal expense management.
It provides money for unexpected situations such as:
- Job loss
- Medical bills
- Major repairs
- Emergency travel
- Unexpected household expenses
Start with a small goal if necessary.
You could first aim for $500 or $1,000, then gradually work toward enough money to cover several months of essential expenses.
Keep emergency savings separate from your everyday spending money when possible.
Step 13: Manage Debt Carefully
Debt payments can consume a large part of your monthly income.
If you have high-interest debt, review your repayment strategy and avoid taking on unnecessary new debt.
Make required payments on time and consider directing additional money toward expensive debt when appropriate.
Before making a purchase using credit, ask yourself whether the purchase is worth the total cost after interest and fees.
Good expense management includes not only controlling what you spend today but also considering how today’s borrowing affects future income.
Step 14: Review Your Expenses Every Month
Your financial situation can change.
Therefore, your expense plan should not remain exactly the same forever.
At the end of every month, review:
- Total income
- Total spending
- Savings
- Debt payments
- Unexpected expenses
- Categories where you overspent
- Categories where you underspent
Then make adjustments for the next month.
A monthly review takes only a short amount of time but can help you stay financially organized.
Simple Ways to Manage Personal Expenses
Here are some practical habits you can start using immediately:
Make a shopping list: Know what you need before entering a store.
Set weekly spending limits: Weekly limits can be easier to follow than monthly limits.
Avoid unnecessary convenience costs: Small convenience purchases can become expensive when repeated.
Use automatic savings: Move money into savings before you have a chance to spend it.
Review subscriptions: Cancel services you no longer use.
Compare prices: Check different sellers before making significant purchases.
Plan meals: Meal planning can reduce food waste and restaurant spending.
Use a spending tracker: Recording expenses keeps your spending visible.
Avoid emotional spending: Do not use shopping as a response to stress or boredom.
Give yourself a reasonable fun budget: A realistic budget is easier to maintain than an extremely restrictive one.
Example of Personal Expense Management
Imagine someone earns $3,000 per month.
After tracking their expenses, they discover they are spending:
- $900 on housing
- $400 on food
- $250 on transportation
- $200 on subscriptions and entertainment
- $300 on shopping
- $250 on debt payments
- $300 on miscellaneous expenses
This totals $2,600, leaving $400.
After reviewing their expenses, they decide to:
- Reduce subscriptions and entertainment by $50
- Reduce shopping by $100
- Reduce miscellaneous spending by $50
Now they have potentially created an additional $200 of room in their monthly budget.
That money can be directed toward savings or debt repayment.
The goal is not necessarily to cut everything. It is to identify spending that does not provide enough value.
Common Expense Management Mistakes
Not Tracking Small Purchases
Small purchases can add up quickly.
Making a Budget That Is Too Strict
A plan that does not allow any personal spending can be difficult to maintain.
Forgetting Annual Expenses
Irregular expenses should be included in your financial planning.
Spending First and Saving Later
If savings are always the last priority, they may never happen.
Ignoring Debt Interest
The cost of borrowing can significantly increase the amount you eventually pay.
Not Reviewing the Budget
A budget should change as your income, expenses, and goals change.
Final Thoughts
Managing personal expenses is not about making your life difficult. It is about making your money work more effectively.
Start by understanding your income, tracking every expense, organizing your spending into categories, and separating needs from wants.
Then create realistic spending limits and regularly review your progress.
Small changes can have a major impact over time. Reducing unnecessary subscriptions, controlling impulse purchases, planning meals, managing recurring expenses, and saving automatically can help create more financial room without requiring extreme lifestyle changes.
The most important step is to start.
You do not need a perfect financial system. You need a simple system that you can follow consistently.
With time, better expense management can help you save more money, reduce financial stress, manage debt, and move closer to your long-term financial goals.
Frequently Asked Questions
What is the best way to manage personal expenses?
Start by tracking your income and expenses. Categorize your spending, create realistic limits, prioritize essential bills, and review your budget every month.
How can I reduce my monthly expenses?
Review recurring subscriptions, restaurant spending, shopping, transportation, and other non-essential expenses. Focus on reducing costs that provide the least value.
Should I track every expense?
Yes. Tracking every expense, at least for a period of time, can help you discover spending patterns and identify areas where you can save.
What is the difference between a need and a want?
A need is something essential for basic living or financial responsibilities. A want is something you would like to have but can live without.
How often should I review my personal expenses?
A monthly review is a good starting point. A quick weekly check can also help you stay on track and catch overspending early.

Leave a Reply